Oil & gas drone insurance
Oil & Gas Drone Insurance for High-Value Inspection Programs
Annual drone insurance reviews for oil and gas inspection contractors and internal corporate UAS teams. Coordinate aviation liability, aircraft values, specialist sensors, and client insurance requirements with Cory Fischer.
For ongoing commercial programs, including a single high-value industrial aircraft or a growing fleet. Single-project and monthly policies are not a fit for this service.
What is oil and gas drone insurance?
Oil and gas drone insurance is insurance reviewed around UAS operations used to inspect energy assets and collect industrial data. The review should address liability arising from flights, physical damage to aircraft, high-value payloads, and the written requirements of the asset owner or client. Coverage depends on the operations accepted by the insurer and the policy issued.
Pipeline and right-of-way inspections
Describe corridor lengths, operating locations, takeoff areas, landowner access, and whether the flights remain within visual line of sight.
Refineries and processing facilities
Discuss work near tanks, structures, active equipment, personnel, and restricted areas. Site permission and operational controls matter alongside insurance.
Specialist inspection payloads
Schedule optical gas imaging, thermal, LiDAR, and other sensors accurately. Replacement value and the treatment of detached equipment need attention.
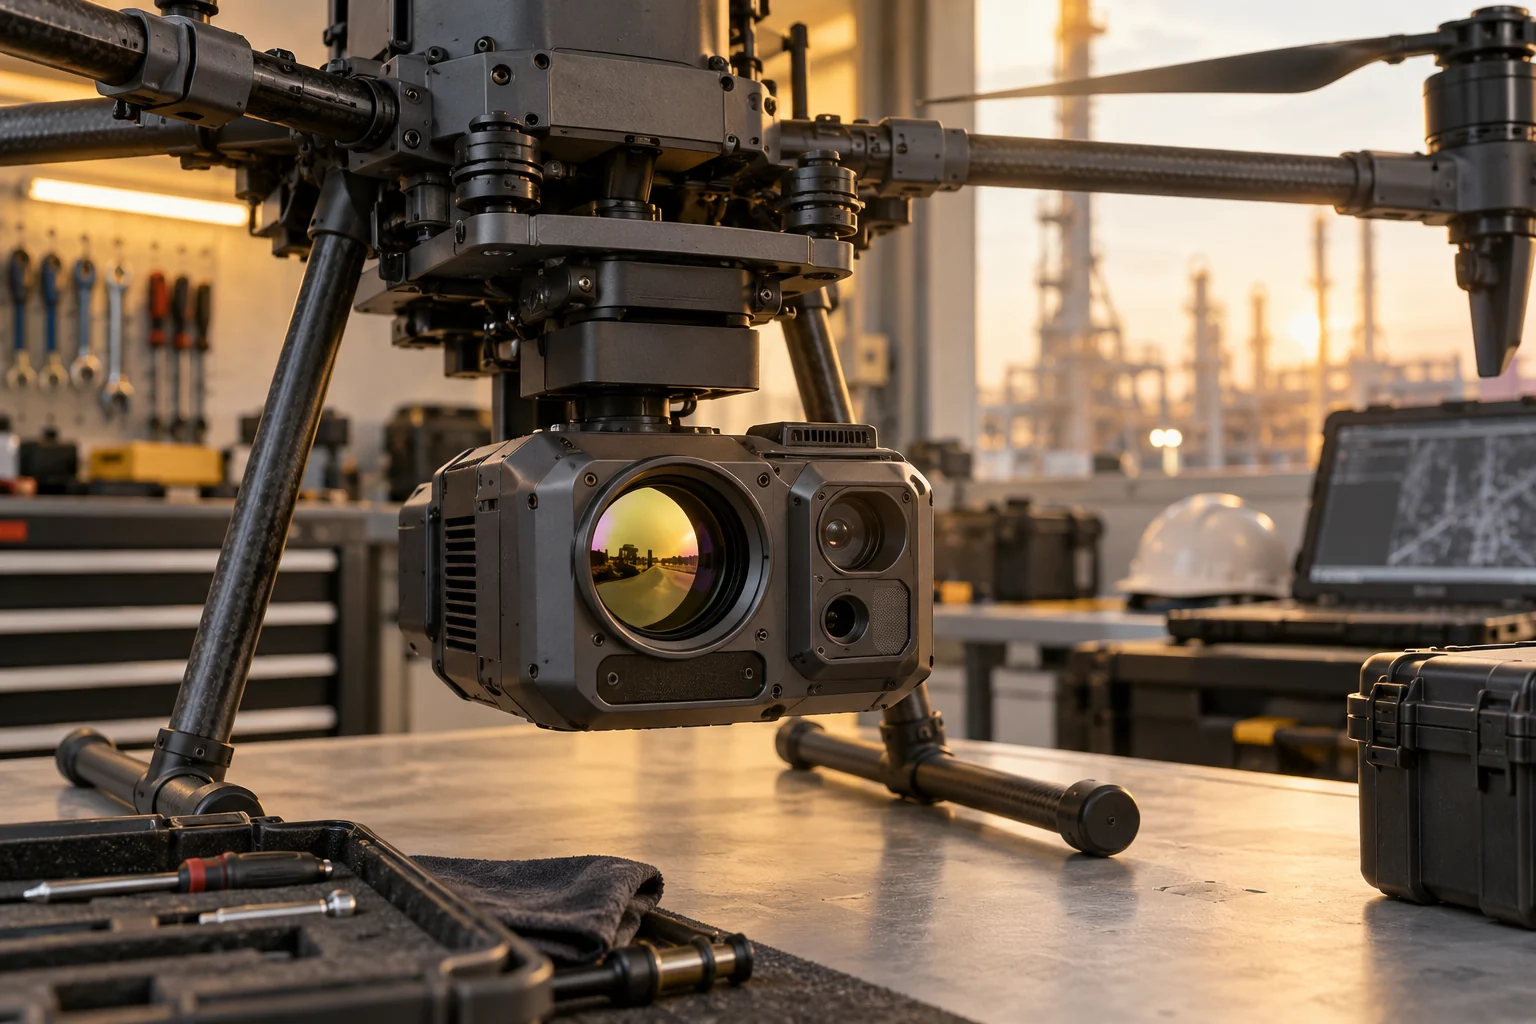
The payload may be as important as the aircraft.
A generic equipment description can leave important questions unanswered. Build a schedule that separates aircraft, sensors, ground stations, batteries, and supporting gear, with values and ownership identified.
Review valuation, deductibles, rented or borrowed equipment, and coverage in flight, transit, and storage. Ask how one incident affecting both the airframe and sensor is handled. Do not assume the same limit or deductible applies to every item.
Explore payload and equipment coverageReview the flight risk and the service you deliver.
Aviation liability
Review third-party bodily injury and property damage exposures arising from the accepted drone operations, including limits, exclusions, and client-required endorsements.
Explore drone liabilityAircraft physical damage
Review scheduled aircraft values, deductibles, repairs, replacement, and the treatment of theft and transport losses under the proposed wording.
Explore aircraft physical damageInspection E&O and pollution questions
An inaccurate report, missed defect, or environmental allegation may raise issues beyond aviation liability. Discuss these separately rather than treating a drone policy as the whole business program.
Discuss the coverage boundariesBefore the next master service agreement, review the insurance language.
Bring the actual MSA, insurance exhibit, and vendor requirements. Review required limits, additional insured status, waiver language, primary and non-contributory wording, and any umbrella or excess requirements against available policy terms.
A certificate is evidence of coverage. It does not change the policy, erase an exclusion, or guarantee that every contractual obligation is insured.
For recurring work across sites, review the whole annual program rather than treating each certificate as a separate insurance decision.
Explore contract insurance requirements
Bring these details to the annual review.
Equipment and people
Aircraft and payload schedules, values, owned or leased status, pilots, training, maintenance controls, and loss history.
Operating scope
Sites and territories, inspection services, flight profiles, relevant authorizations, subcontracted work, and changes planned for the coming year.
Contracts and timing
Current policies, renewal date, insurance exhibits, required limits, and the entities that need to be insured.
Questions before you insure the program
Can an annual policy cover an internal oil and gas drone team?
An annual program can be reviewed for an internal corporate team or an independent inspection contractor. Disclose aircraft, pilots, subsidiaries, operating territories, and actual missions. The insurer determines eligibility and which entities and operations can be covered.
Does drone liability cover losses from an inaccurate inspection report?
A bodily injury and property damage policy may not address a client’s purely financial loss from an inaccurate survey, missed defect, or inspection recommendation. Review professional liability or errors and omissions separately and check aviation-related exclusions and how the policies interact.
Are methane detection, thermal, and LiDAR sensors covered with the aircraft?
Do not assume every payload is included in the aircraft value. Review the equipment schedule, valuation, attachment, deductibles, and coverage while mounted, detached, transported, or stored. The policy wording controls.
Can the program include BVLOS pipeline inspections?
Disclose the planned flight profile and applicable FAA approvals before quoting or changing operations. Regulatory permission and insurance acceptance are separate. BVLOS coverage is subject to underwriting and policy terms.
Practical reading for inspection programs
Read the Oil & Gas Insurance Review GuideRelated: Utilities & energy inspections · Inspection & mapping · FAA Part 107 waiver guidance